
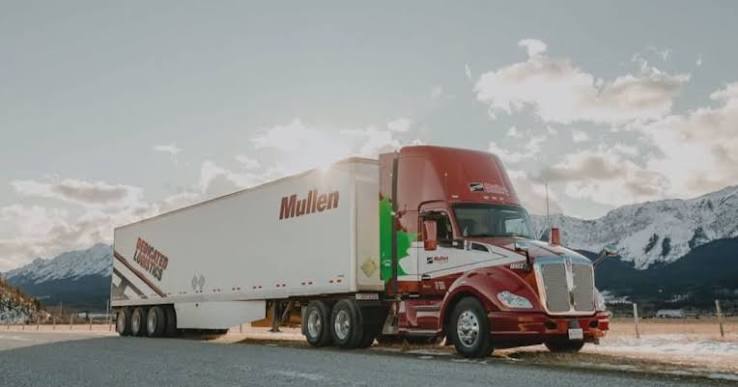
Mullen Group earnings moved sharply higher in the third quarter of 2026, giving investors a fresh read on the health of Canada’s freight economy. The Alberta-based trucking and logistics company reported a quarterly profit of $51.5 million, compared with $33.2 million in the same period a year earlier, while revenue climbed 16 per cent from the prior-year quarter. The results were released on October 22 and arrive at a time when many Canadian businesses are still navigating trade uncertainty with the United States.
A Closer Look at the Mullen Group Earnings Numbers
The headline profit figure represents an increase of roughly 55 per cent over the year-earlier result, a substantial gain for a company that operates in a sector known for thin margins and sensitivity to the business cycle. Just as notable is that the bottom line grew considerably faster than the top line. Revenue growth of 16 per cent is solid on its own, but profit rising at more than three times that pace suggests the company was able to convert additional business into earnings more efficiently than it did a year ago.
Readers who want the original summary can review the third-quarter results reported by The Canadian Press, which outlines the profit and revenue changes. Detailed segment breakdowns and per-share figures are typically published in the company’s own quarterly filings, and investors evaluating the stock should consult those documents for a complete picture of margins, cash flow and balance sheet strength.
Who Mullen Group Is and Why It Matters
Mullen Group is one of the larger publicly traded transportation and logistics providers in Canada. Headquartered in Okotoks, Alberta, and listed on the Toronto Stock Exchange, the company operates through a network of business units that span less-than-truckload freight, logistics and warehousing, and specialized services tied to industrial and resource customers. It is led by Murray Mullen, who serves as chair and senior executive officer and has guided the company through several economic cycles.
The company’s business model has long relied on acquiring regional operators and allowing them to keep their own brands and management teams while benefiting from the parent company’s capital and scale. That decentralized structure has made Mullen something of a bellwether for freight activity across the country, particularly in Western Canada, where its roots in oilfield and industrial services run deep.
Trade and Mining as Long-Term Growth Drivers
The company has indicated that it expects long-term gains from trade and mining activity, especially in northern and western Canada. That outlook lines up with a broader national conversation about building infrastructure, expanding critical minerals production and diversifying export routes beyond the United States. Projects in the North and in resource-rich provinces require enormous volumes of equipment, materials and supplies to be moved over long distances, often in difficult terrain. Specialized carriers with experience in those conditions stand to benefit if development accelerates.
Mining in particular has drawn renewed policy attention in Canada as governments look to secure supply chains for minerals used in batteries, electronics and defence applications. While new mines can take many years to move from discovery to production, the logistics work associated with exploration, construction and eventual operations can provide steady demand for trucking and support services over long periods.
What the Results Signal for the Canadian Economy
Trucking companies sit at the heart of the physical economy. When manufacturers, retailers, builders and resource producers are shipping more goods, carriers tend to see it first. A meaningful jump in Mullen’s profit and revenue suggests that, at least within the company’s footprint, freight demand has held up better than many feared during a period marked by tariff disputes and softer consumer spending.
That said, investors should be careful about drawing sweeping conclusions from a single company’s quarter. Revenue growth can come from acquisitions as well as from organic increases in shipping volumes or pricing. Without separating those factors, it is difficult to know how much of the improvement reflects underlying economic strength versus the company’s own expansion strategy. Analysts will likely focus on that distinction in the weeks ahead.
Implications for Investors and the TSX
For shareholders, the latest Mullen Group earnings report offers several points worth weighing. First, the company has historically paid a regular dividend, which has made it popular with income-focused investors. Stronger profits can support the sustainability of that payout, although dividend decisions depend on many factors, including debt levels and capital spending plans.
Second, the results add to the picture of how Canadian industrial stocks are faring as the country adjusts to a more uncertain trade relationship with its largest partner. Transportation names on the TSX are often viewed as cyclical, meaning their share prices can swing with expectations for economic growth. A strong quarter may help ease concerns about a sharp slowdown in freight, but sentiment can shift quickly if trade tensions escalate or commodity prices fall.
Third, the company’s emphasis on northern and western development ties its fortunes to resource policy. Investors who believe Ottawa and the provinces will follow through on faster permitting and major infrastructure projects may see Mullen as a way to gain exposure to that theme without owning mining or energy producers directly. Those who are skeptical about the pace of project approvals may prefer to wait for clearer evidence that new activity is materializing.
Risks to Watch in the Months Ahead
Despite the encouraging numbers, several risks remain. Fuel costs, labour availability and insurance expenses can all squeeze margins in trucking. Competition in the freight market is intense, and pricing power can erode quickly when capacity exceeds demand. Cross-border trade policy also remains a wildcard, since changes in tariffs or regulations can alter shipping patterns between Canada and the United States with little warning.
Interest rates matter as well. Companies that grow through acquisitions often rely on borrowing, and the cost of that financing affects how attractive future deals look. Lower rates in Canada over the past couple of years have eased some of that pressure, but the outlook for monetary policy will continue to influence capital allocation decisions across the sector.
Conclusion
Mullen Group delivered a strong third quarter, with profit rising to $51.5 million and revenue up 16 per cent from a year earlier. The results point to resilient freight demand in parts of the Canadian economy and reinforce management’s long-term confidence in trade and mining activity across the North and West. For investors tracking Mullen Group earnings, the key questions now are how much of that growth is sustainable and whether Canada’s resource and infrastructure ambitions translate into steady work for the country’s carriers.